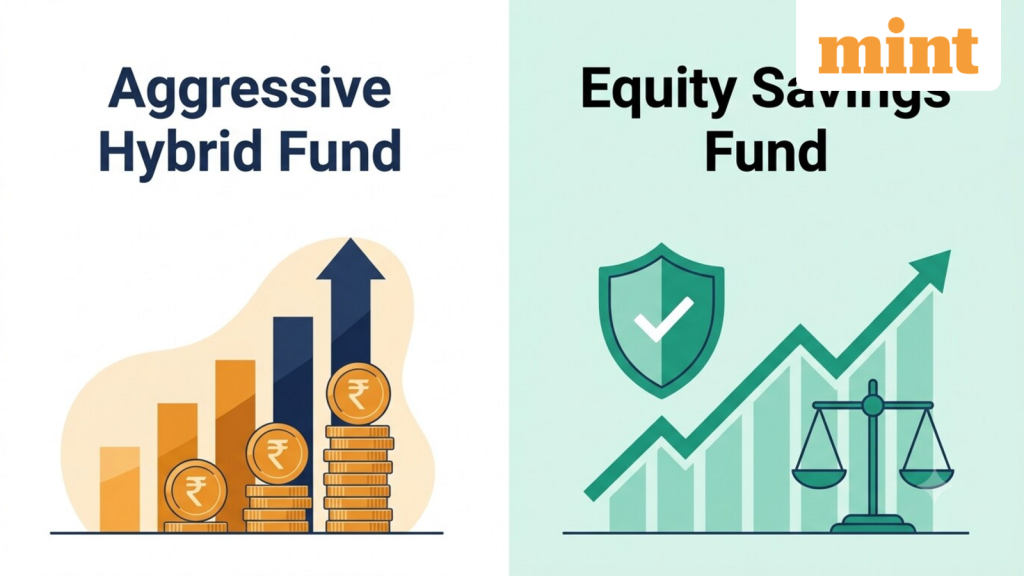
Aggressive hybrid and equity savings mutual funds both operate under a minimum 65% equity allocation in India, but they are built for different investment experiences. The first category takes largely unhedged equity exposure for long-term growth; the second combines equity, arbitrage and debt to reduce direct market risk. Their returns over the past decade reflect that divide, with aggressive hybrid funds ahead over three, five and 10 years, while equity savings funds have done better over the past year.
What SEBI’s category rules require
Under the Securities and Exchange Board of India’s mutual fund categorization norms, an aggressive hybrid fund must keep 65% to 80% of total assets in equity and equity-related instruments and 20% to 35% in debt. Most of the equity exposure is unhedged, so stock market movements drive performance more directly. The debt sleeve offers some cushion when equity markets are volatile.
Equity savings funds also need at least 65% in equity and equity-related instruments, but the portfolio is structured differently. They must maintain net long equity exposure of 15% to 40% of total assets and at least 10% in debt. Fund managers use arbitrage by buying a stock in the cash market while simultaneously selling its futures contract to capture price differences. Only the 15%-40% net long portion is directly exposed to equity market direction. The rest is managed through hedged positions and debt.
Risk labels and volatility
Equity savings funds generally carry lower risk because of that hedged equity and debt mix. Value Research’s list shows almost all aggressive hybrid funds with a “very high risk” label, with one scheme in the “high risk” category. Equity savings funds range from “low to moderate risk” to “moderately high risk.”
Standard deviation, which measures how much returns fluctuate, makes the gap clearer. Aggressive hybrid funds have a category average standard deviation of 12.14, against 5.06 for equity savings funds. A higher figure means greater volatility.
Returns over one, three, five and 10 years
Category average compound annual growth rates as of 13 November 2026 show the trade-off:
- One year: aggressive hybrid 1.94%; equity savings 3.63%.
- Three years: aggressive hybrid 10.99%; equity savings 8.15%.
- Five years: aggressive hybrid 8.88%; equity savings 7.02%.
- 10 years: aggressive hybrid 11.37%; equity savings 7.89%.
The figures indicate that aggressive hybrid funds have delivered stronger longer-horizon returns, while equity savings funds have led over the latest one-year period. The one-year result also illustrates that lower volatility does not automatically mean lower returns in every market phase.
How investors can read the difference
The choice depends on risk appetite and investment horizon. Aggressive hybrid funds may suit investors seeking higher long-term growth potential who can tolerate a higher level of risk. Equity savings funds may appeal to investors who want a mix of hedged equity, unhedged equity, arbitrage and debt exposure.
Arbitrage strategies can reduce directional equity market risk, but they are not entirely risk-free. Returns can be affected by changes in price differences, liquidity and broader market conditions. Investors should also note that category averages are not a promise of future performance and that individual schemes can vary.
The educational comparison is not investment advice. Investors should consult a SEBI-registered advisor before making investment decisions.