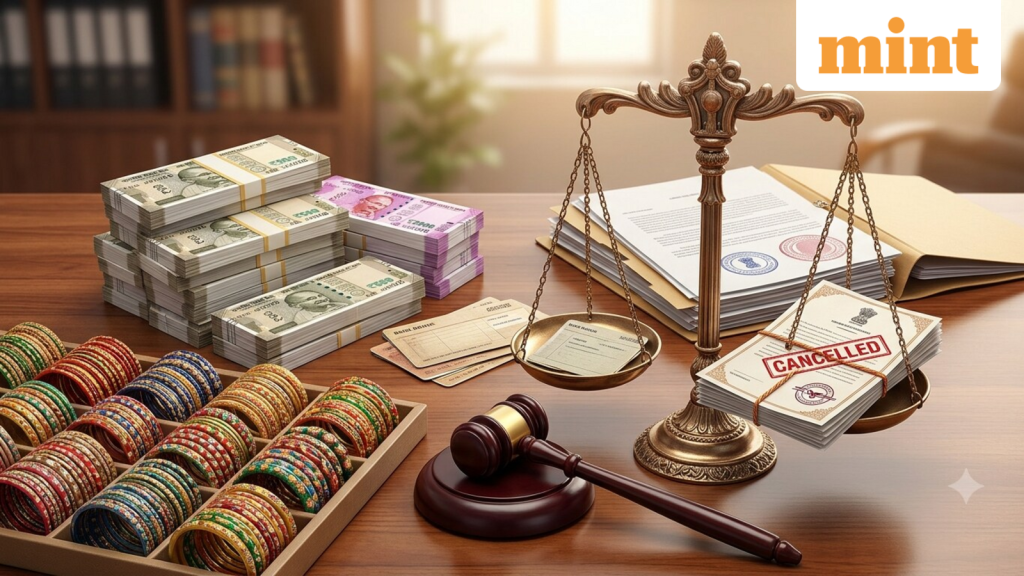
The Agra bench of the Income Tax Appellate Tribunal (ITAT) has deleted a ₹3.69 crore addition made to the income of a Firozabad-based woman after finding that the deposits in her two bank accounts were not established to be her own income. In its order dated 4 November 2026 in Pooja Agarwal vs Income Tax Officer, ITA No. 309/Agr/2026, the tribunal set aside the addition made under Section 69A of the Income Tax Act, 1961, and allowed her appeal.
The case covered assessment year 2018-19. Agarwal had filed her return declaring total income of ₹3.20 lakh. During scrutiny, the assessing officer found ₹3.69 crore deposited in her two bank accounts, far above the ₹4.98 lakh turnover reported in the return. The officer treated the entire amount as unexplained money under Section 69A.
Agarwal’s explanation was that she ran a commission-based business. She facilitated payments between bangle buyers in different parts of India and traders in Firozabad. Buyers deposited cash into her accounts; she then withdrew the money and helped make payments to local suppliers. She said she charged ₹500 for every ₹1 lakh handled and had declared commission income of ₹1.85 lakh under the presumptive taxation scheme in Section 44AD.
The assessing officer rejected that explanation. The department questioned why buyers from across the country would route cash through her accounts rather than pay traders directly. It also said she had not provided complete party-wise details such as names, addresses and other information needed to verify the transactions. The officer further found that she had not maintained adequate documentary evidence to establish the identity of the parties or the genuineness of the transactions. The entire ₹3.69 crore was therefore treated as unexplained income, and the Commissioner of Income Tax (Appeals) upheld the addition. Agarwal then moved the ITAT.
The tribunal examined the bank transactions and found that the deposits were followed by substantial cash withdrawals. Total deposits were ₹3,69,92,943, while cash withdrawals stood at ₹3,73,69,422. It also considered the assessment order for the immediately preceding year, 2017-18, in which the assessing officer had acknowledged that Agarwal earned commission income.
The tribunal noted that the department had not placed evidence on record to show that Agarwal carried on an independent business capable of generating such a large amount of undisclosed income. It also held that her explanation about facilitating transactions between bangle traders in different cities and suppliers in Firozabad could not be rejected outright, especially given the transaction pattern and the earlier assessment. The deposits could not, therefore, be treated as her undisclosed income under Section 69A merely because of the amount involved. The tribunal deleted the addition of ₹3,69,92,943 and decided the appeal in her favour.
Section 69A allows an assessing officer to treat money, bullion, jewellery or other valuable assets as unexplained income when a taxpayer is found to be their owner but cannot satisfactorily explain their source. The ruling does not mean that large bank deposits automatically become the account holder’s taxable income. Ownership of the money, the nature of the transactions and the available evidence must also be examined.
The decision also does not give taxpayers a route to avoid tax on unexplained deposits by simply saying they handled someone else’s money. Supporting evidence and the facts of each case remain central. In Agarwal’s case, the tribunal found that the department had not established that the deposited funds belonged to her, and it set aside the addition.