In a significant relief for property owners navigating long-term capital gains tax, the Mumbai bench of the Income Tax Appellate Tribunal has ruled that an investor who sells commercial premises and acquires two residential flats on different floors within the same building can claim capital gains tax exemption under Section 54F of the Income-tax Act. The tribunal allowed a contested deduction of ₹2.51 crore, holding that multiple residential units can be regarded as a single residential house when the factual arrangement and circumstances demonstrate that they serve as collective living accommodation for the taxpayer’s family.
The Property Sale and Capital Gains Assessment
The dispute arose in the case of Sunil Indravadan Shah versus the Income Tax Officer, Ward 19(3)(1) (ITA No. 7276/MUM/2025), which was decided on August 24, 2026. The taxpayer held six commercial units located at Solitaire Chambers on Kalbadevi Road in Mumbai. Between June 13, 2019, and July 5, 2019, the taxpayer executed sale deeds for these commercial properties, generating a cumulative net sales consideration of ₹5.32 crore. This transaction resulted in long-term capital gains computed at approximately ₹4.97 crore.
To mitigate the substantial tax liability arising from the transfer of these capital assets, the taxpayer sought relief under Section 54F by deploying the entire net proceeds into residential real estate. On September 29, 2020, he finalized the purchase of two separate residential apartments in a redevelopment project named 22 Dholera, located in Parel, Mumbai. Both apartments were acquired from the same builder, Safal Realtors & Developers Private Limited.
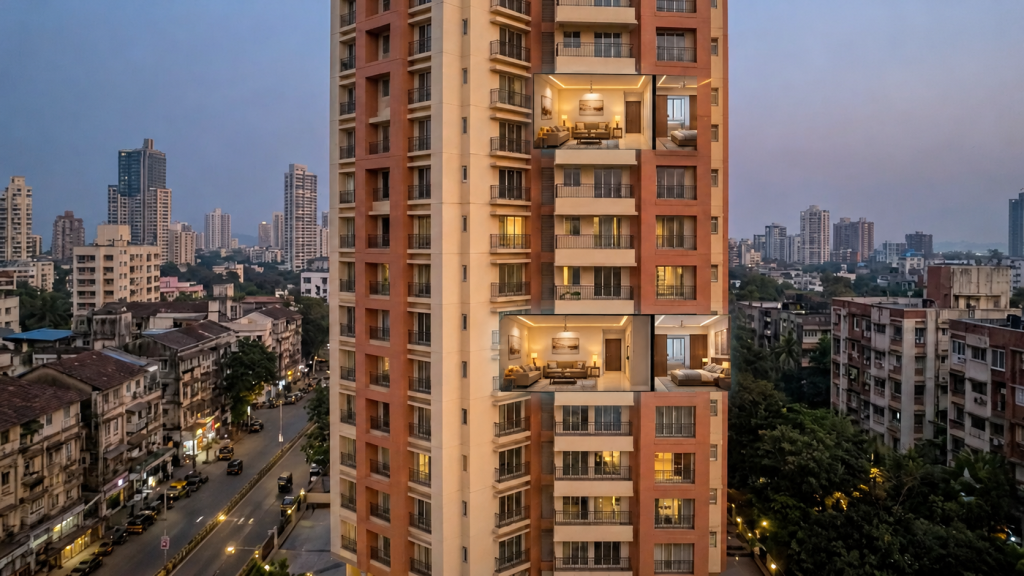
The two properties comprised Flat A-601 on the sixth floor and Flat A-1801 on the eighteenth floor, both situated in Wing A of the building. Each apartment measured an identical carpet area of 1,334.19 square feet and carried an identical purchase consideration of ₹2.65 crore. Across both apartments, the total investment amounted to ₹5.30 crore, against which the taxpayer claimed an exemption of ₹4.97 crore under Section 54F on his return of income.
Revenue Department Objections and Initial Disallowance
During the assessment proceedings, the assessing officer took the position that the statutory language of Section 54F limits relief to investment in “a residential house” in India. The tax authority observed that the taxpayer had executed two independent sale agreements, paid separate stamp duties and registration fees, and purchased apartments situated twelve floors apart. Each unit possessed its own separate entrance, independent utility connections, and distinct municipal identification.
Based on these physical and documentation factors, the assessing officer concluded that the taxpayer had acquired two distinct residential properties rather than one. Consequently, the officer permitted the Section 54F exemption for only one of the flats and disallowed a deduction of ₹2.51 crore attributable to the second flat. The taxpayer appealed the assessment, but the Commissioner of Income Tax (Appeals) at the National Faceless Appeal Centre upheld the assessing officer’s decision, reiterating that separate legal registrations and physical separation across different floors precluded treatment as a single residential unit.
Taxpayer Contentions Before the Appellate Tribunal
Aggrieved by the appellate order, the taxpayer approached the Mumbai ITAT. Counsel for the taxpayer argued that the statutory phrase “a residential house” should not be interpreted in a rigid, hyper-technical manner that defeats the beneficial purpose of the legislation. The taxpayer highlighted that both apartments were booked on the same day, purchased from the exact same developer, situated in the same residential wing, and finalized under identical terms.
The taxpayer explained that due to high property density and structural layout constraints in Mumbai, finding large, contiguous, or horizontally adjacent flats in modern residential towers is often impractical. The family required adequate space to reside together, and purchasing two flats within the same building wing was the most feasible arrangement. Furthermore, specific personal circumstances were placed on record, including medical documentation regarding the taxpayer’s wife, whose physical mobility restrictions necessitated specialized living arrangements while keeping the extended household under one roof.
Tribunal Findings and Legal Precedents
The Mumbai ITAT analyzed the statutory scope of Section 54F alongside binding judicial interpretations of the expression “a residential house.” The tribunal placed primary reliance on the landmark judgment of the Delhi High Court in Commissioner of Income Tax versus Gita Duggal (2013). In that ruling, the High Court established that the term “a residential house” does not restrict an assessee to a single self-contained physical flat. A building consisting of multiple independent units or distinct living floors can qualify as one residential house for the purpose of capital gains relief if it functions as a consolidated domestic habitation.
The tribunal also referenced the Delhi High Court decision in Principal Commissioner of Income Tax versus Lata Goel, which reinforced a purposive, wider interpretation of Section 54F. Evaluating the facts at hand, the tribunal noted several undeniable points of convergence: identical execution dates, the same developer, the same tower and wing, identical carpet areas, and matching acquisition values. The tribunal determined that the physical placement on different floors does not, by itself, negate the character of a property being utilized as unified family housing. Furthermore, separate registration documents and individual entrance doors are common administrative requirements in multi-story developments and cannot override the substantive nature of the accommodation.
Finding that the revenue authorities adopted an excessively restrictive approach, the ITAT set aside the order of the Commissioner of Income Tax (Appeals) and instructed the assessing officer to grant the Section 54F deduction of ₹2.51 crore.
Key Provisions and Conditions of Section 54F
Section 54F is an incentive provision designed to encourage investment in residential housing. It applies when an individual or a Hindu Undivided Family (HUF) transfers any long-term capital asset other than a residential house—such as commercial real estate, industrial plots, vacant land, gold, or unlisted shares—and reinvests the proceeds in a residential house in India.
To qualify for the exemption, specific statutory timelines must be met:
- The taxpayer must purchase the new residential house within one year before or two years after the date of transfer of the original asset, or
- Construct the new residential house within a period of three years from the date of the original transfer.
If the entire net sales consideration received from the sale is reinvested in the new property, the entire eligible capital gains amount is exempt from income tax. If only a fraction of the net consideration is deployed, the exemption is calculated on a proportionate basis using the statutory formula. Furthermore, the statute mandates that the taxpayer must not own more than one residential house (other than the newly acquired property) on the date of the transfer of the original capital asset, nor purchase another residential house within one year or construct one within three years of that date. In addition, the Finance Act has capped the maximum investment considered for exemption under Section 54F at ₹10 crore.
Implications for Real Estate Investors
While the Mumbai ITAT decision provides clear judicial support for taxpayers acquiring multiple apartments in the same residential complex, tax experts emphasize that relief is contingent on surrounding facts. The ruling does not grant an unqualified license to buy unconnected investment properties and claim aggregated exemptions. Income tax authorities continue to evaluate whether multiple units serve a genuine domestic purpose, the closeness of the transactions, and the bona fide intention of the family unit.